Benchmark: Comparing the Monte Carlo Method with Nonparametric Bootstrapping
Ivan Jacob Agaloos Pesigan
2026-11-05
Source:vignettes/benchmark.Rmd
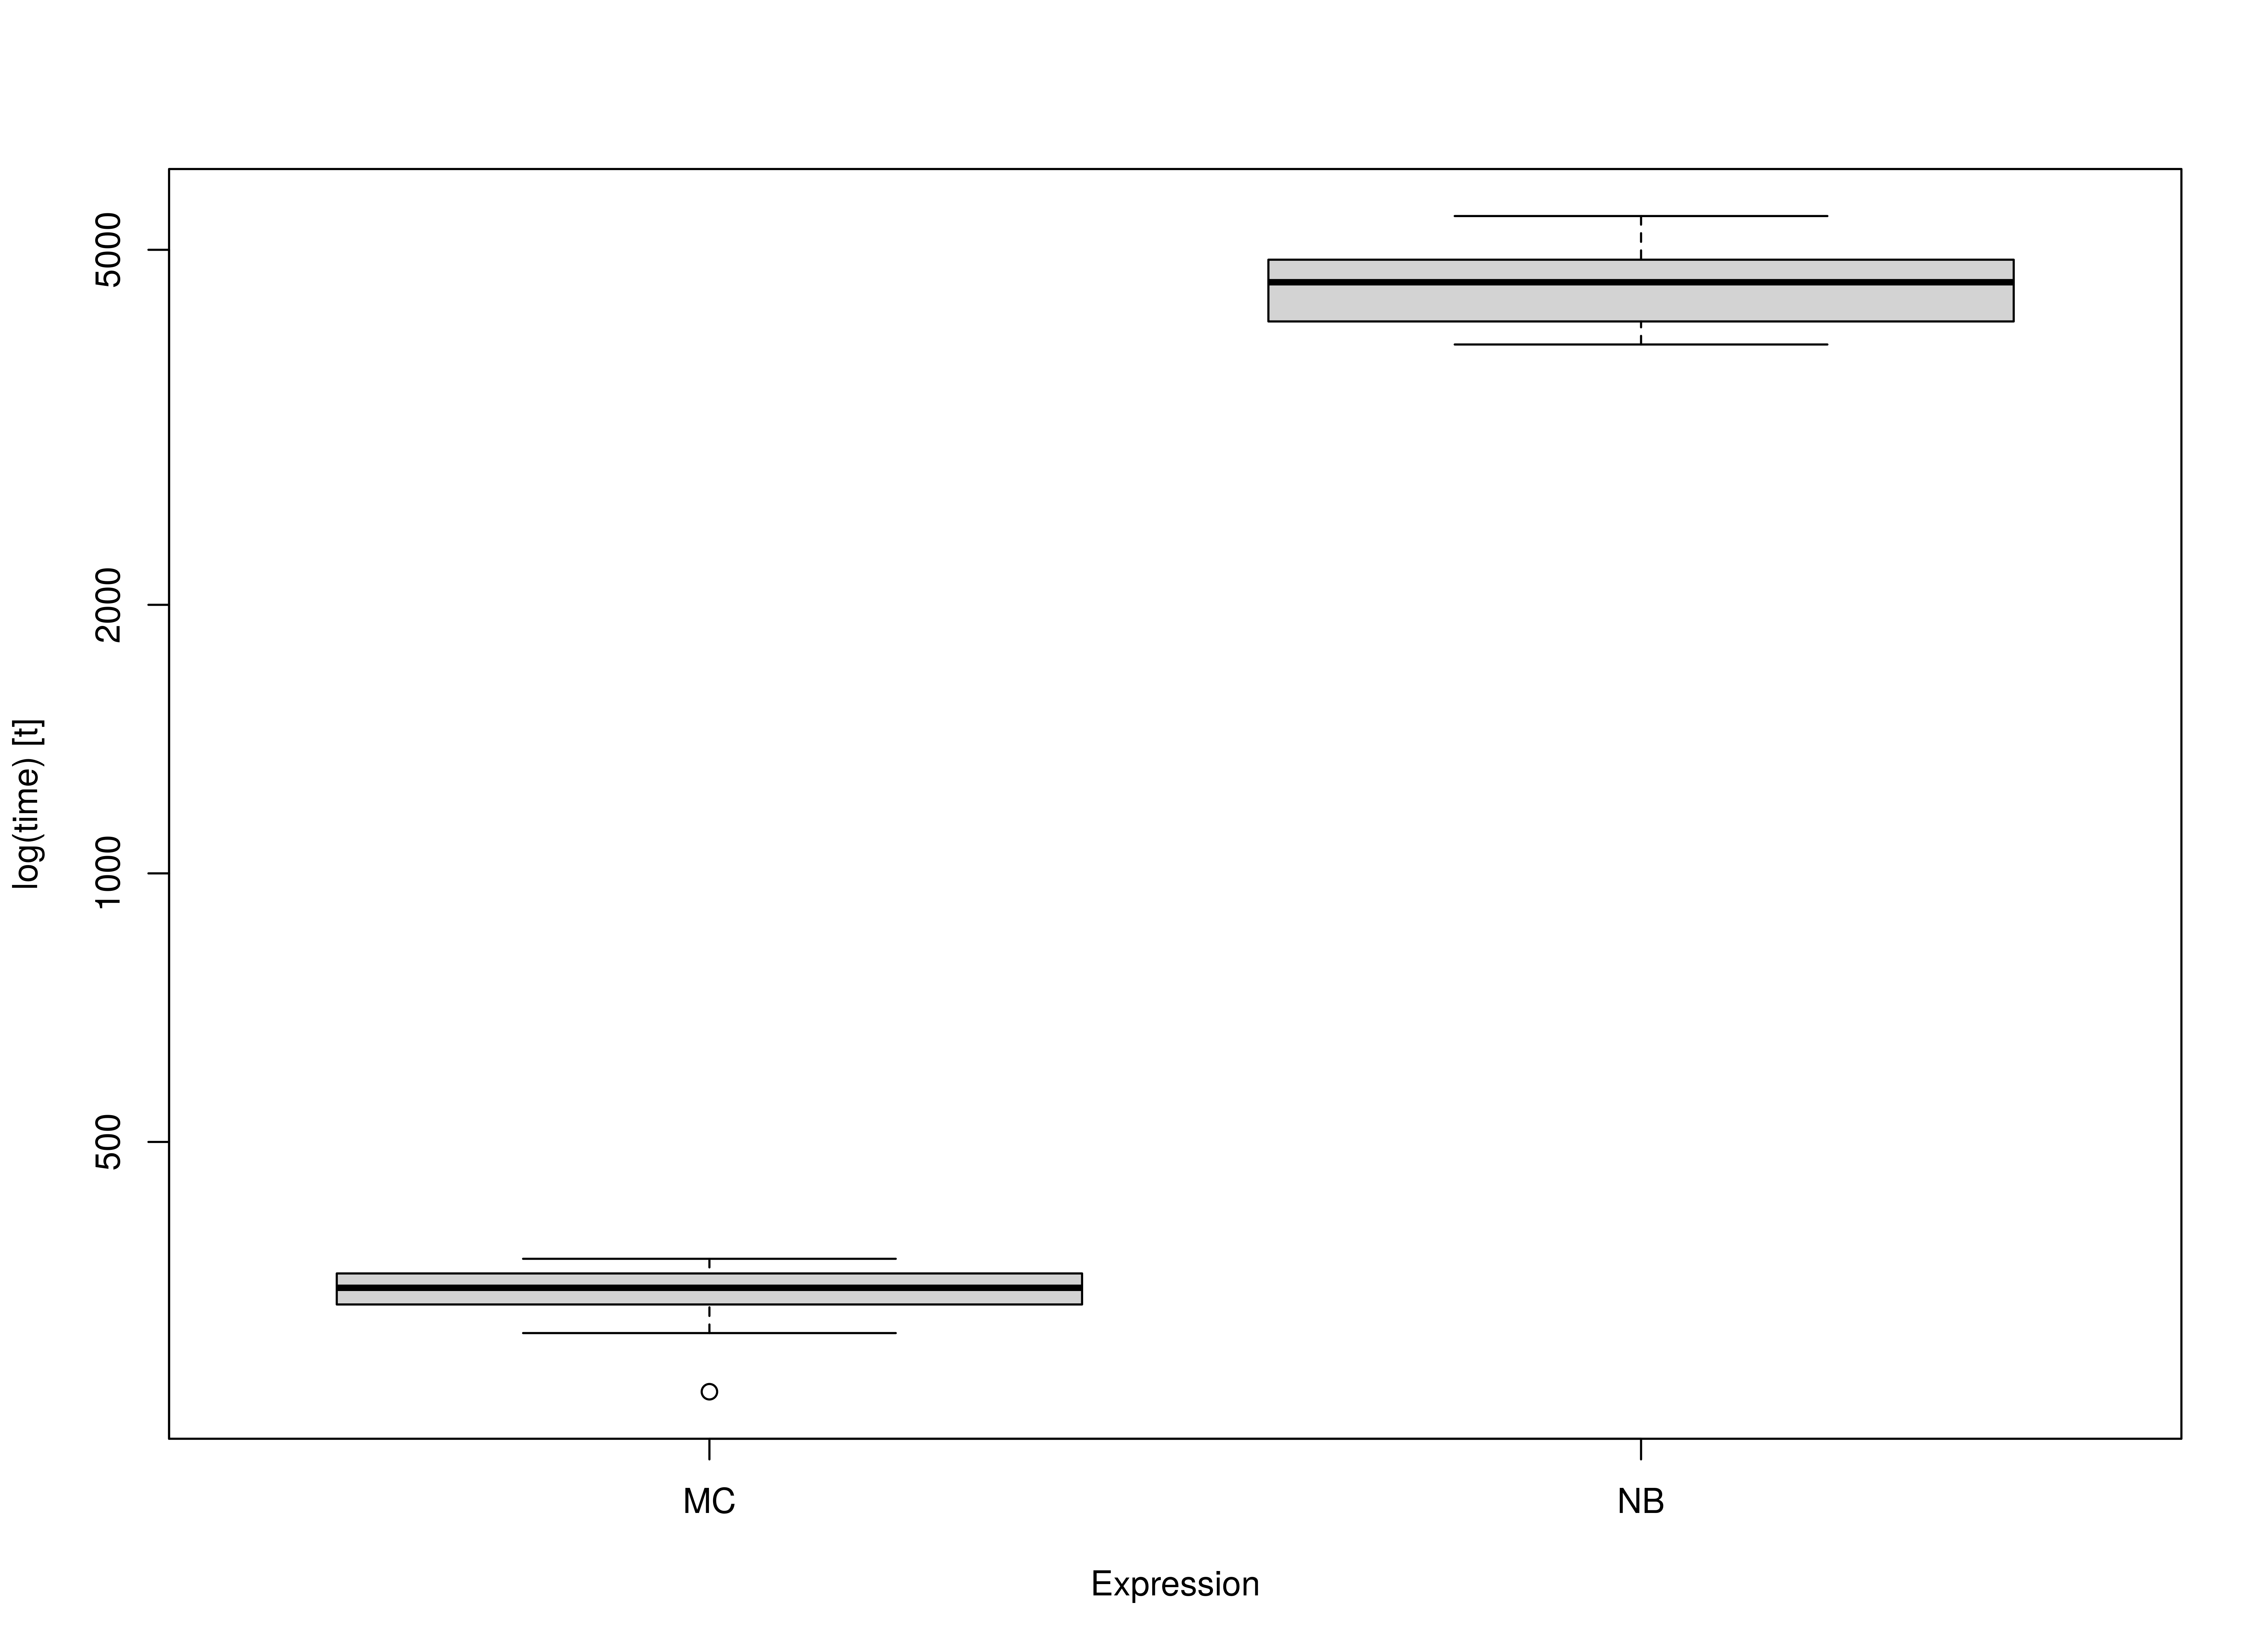
benchmark.RmdWe compare the Monte Carlo (MC) method with nonparametric bootstrapping (NB) for standardized regression coefficients. In this example, we use the data set and the model used in betaMC: Example Using the BetaMC Function.
library(betaMC)
library(boot)
library(microbenchmark)
The BetaMC() function is used to generate MC confidence
intervals. The BetaNB() function is used to generate NB
confidence intervals.
BetaNB <- function(formula, data, B) {
  statistic <- function(formula, data, indices) {
    return(
      coef(lm(formula = formula, data = as.data.frame(scale(data[indices, ]))))[-1]
    )
  }
  return(boot.ci(boot(data = data, statistic = statistic, formula = formula, R = B)))
}
Data and Model
df <- betaMC::nas1982Benchmark
Arguments
| Variables | Values | Notes |
|---|---|---|
| R | 5000 | Number of Monte Carlo replications. |
| B | 5000 | Number of bootstrap samples. |
benchmark <- microbenchmark(
  MC = {
    formula <- "QUALITY ~ NARTIC + PCTGRT + PCTSUPP"
    object <- lm(formula = formula, data = df)
    mc <- MC(object = object, R = R, type = "mvn")
    BetaMC(object = mc)
  },
  NB = {
    formula <- "QUALITY ~ NARTIC + PCTGRT + PCTSUPP"
    object <- lm(formula = formula, data = df)
    BetaNB(formula = formula, data = df, B = B)
  },
  times = 10
)
Summary of Benchmark Results
summary(benchmark, unit = "ms")
#>   expr        min         lq       mean     median       uq        max neval
#> 1   MC   10.76533   11.02513   11.73928   11.17096   11.401   17.10782    10
#> 2   NB 1934.13308 1951.13237 1971.06786 1961.22100 2002.657 2008.81859    10
Summary of Benchmark Results Relative to the Faster Method
summary(benchmark, unit = "relative")
#>   expr      min       lq     mean   median       uq     max neval
#> 1   MC   1.0000   1.0000   1.0000   1.0000   1.0000   1.000    10
#> 2   NB 179.6631 176.9714 167.9037 175.5642 175.6564 117.421    10